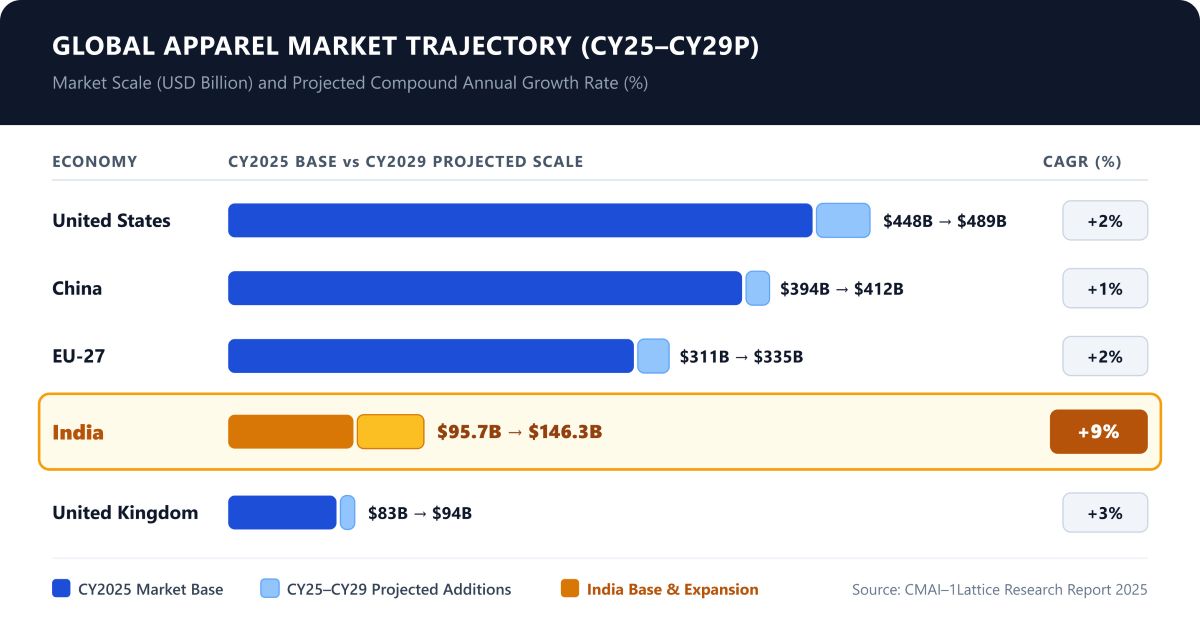
The domestic apparel market in India has officially decoupled from traditional metro-first assumptions, establishing a realistic empirical base of $95.7 billion (INR 8.08 lakh crore) in CY2025. Set to expand to $146.3 billion (INR 12.33 lakh crore) by CY2029 at a compound annual growth rate (CAGR) of 9%, the sector is comfortably outstripping major Western and Asian powerhouses, where mature markets such as the United States ( 448 billion base, 2%CAGR) , China ( 394 billion base, 1% CAGR), and the EU-27 ($311 billion base, 2% CAGR) are expanding at marginal rates.
The findings, unveiled by the Clothing Manufacturers Association of India (CMAI) in its benchmark “Indian Apparel Market Size: A Consumer Research Report 2025”, executed in collaboration with research consulting firm 1Lattice; reset several persistent industry myths. Rather than depending on mechanical spreadsheet projections that routinely overstated domestic consumption upwards of $118 billion by compounding historic 1980s data, the latest report is grounded in extensive ground-level fieldwork. The research team conducted face-to-face computer-assisted personal interviewing (CAPI) across 10,929 households spanning 16 states between November 2025 and February 2026, triangulating consumer diaries with brand performance data and secondary industry filings.
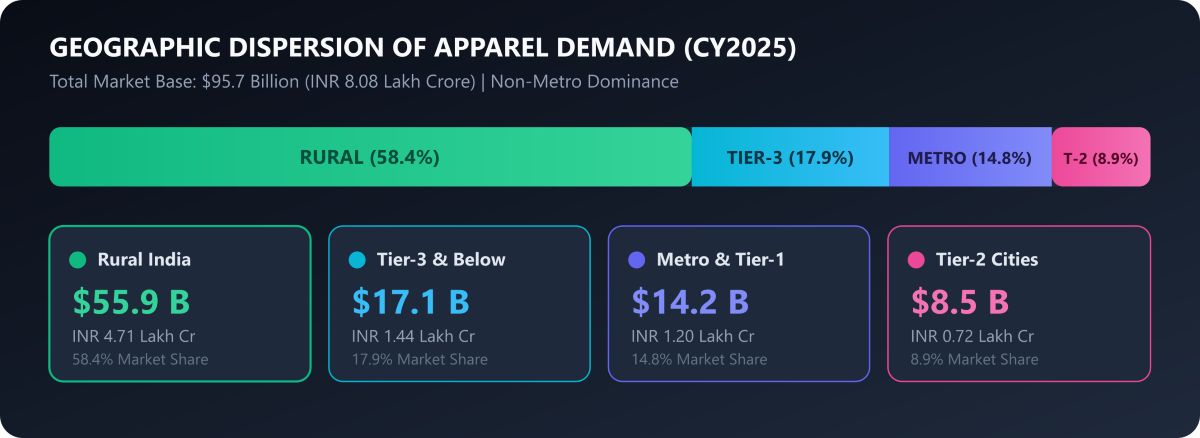
The single biggest commercial surprise is the sheer scale of non-urban consumption. Rural India generated $55.9 billion (INR 4.71 lakh crore), or 58.4% of overall domestic clothing consumption in CY2025. Tier-3 and smaller municipal towns brought in another $17.1 billion (17.9%), whereas traditional metro powerhouses and Tier-1 cities accounted for merely $14.2 billion (14.8%), followed by Tier-2 municipal centers at $8.5 billion (8.9%).
"The current apparel market, our survey has estimated to be 96.7 billion US dollars," said Rahul Mehta, Chief Mentor of CMAI, pointing to the significance of empirical sizing over speculative compounding. "The importance of this is because this is the first time after several years that an actual field study has shown these figures. Otherwise, what used to happen was that somebody did some survey on some basis and arrived at a figure in 1980, and then every year people just kept adding 5% or 10% to that figure. If you go by that, Indian domestic apparel consumption is close to about 118 billion dollars. But our study has shown that it is not so much; it is 96 billion dollars."
Addressing the operational shift of national retailers toward smaller districts, Mehta added: "The interesting part is that in 2025, the rural market constitutes 58% of our total market. Almost all brands and retailers are opening their stores in Tier-2 and Tier-3 cities in the rural markets, alongside the growth of newer retail outlets like Zudio, Style Union, etc., which seem to be focusing more on the non-metro markets."
CMAI President Santosh Katariya reinforced this strategic imperative: "The next phase of growth for India’s apparel industry will increasingly come from markets beyond the metros. Tier-2 and Tier-3 cities are already contributing significantly to apparel consumption, while rising aspirations are creating demand for a wider choice of brands, formats, and fashion. The opportunity now is to build propositions that are contemporary, relevant, and accessible to the emerging Indian consumer, while deepening distribution and retail presence across these markets."
The Myth of Western Dominance: East India’s quiet supremacy
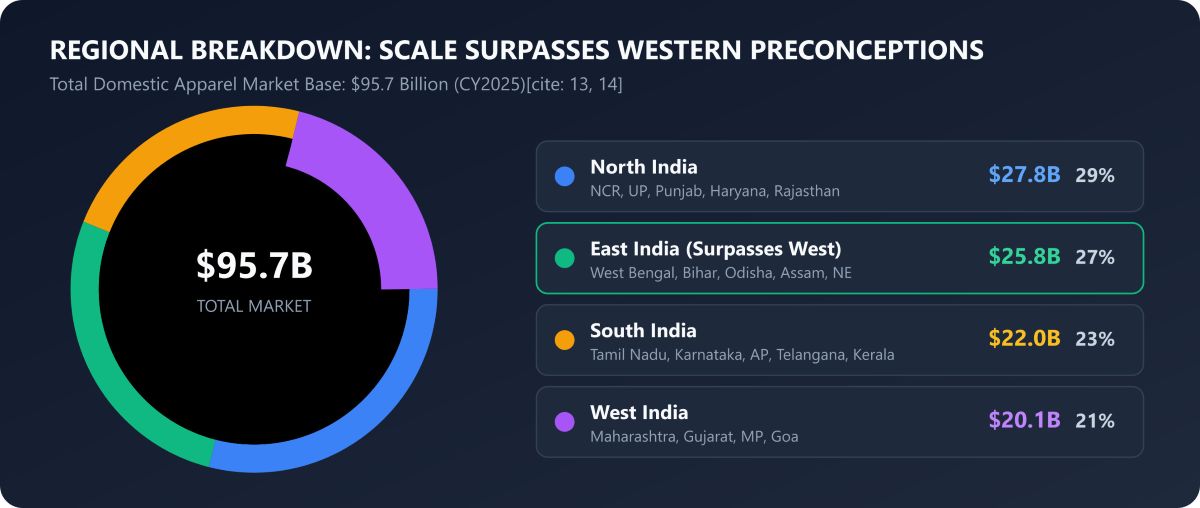
Long seen by retail corporate headquarters as a secondary, highly price-sensitive market, Eastern India has emerged as the country’s second-largest regional apparel consumption hub, generating $25.8 billion (INR 2.17 lakh crore) to capture 27% of nationwide sales. It ranks just behind North India ( 27.8 billion, 29%), while surpassing the South (22.0 billion, 23%) and decisively overtaking the traditionally style-dominant West ($20.1 billion, 21%).
This geographic ranking is explained by sheer population weight combined with unwavering cultural consumption habits, which contrast sharply with western metro consumer behaviour. While per capita expenditure in western metropolises like Mumbai is spread across diverse leisure activities and dining out, shopping remains the primary vehicle for discretionary celebration across the East.
"If at all I can pinpoint one misconception which is in the industry today, it is the sort of less importance being given to the East market," remarked Mehta during the Q & A with media "I remember when I launched my 109°F brand back in 1982, surprisingly the North-East was my strongest market. When I launched in Shillong, Dehradun, and those areas, people were actually laughing at me. But brands who have neglected the East are doing it at their own cost. In Mumbai, most people buy far more during end-of-season sales than they do during Diwali. But Durga Puja in Bengal and Eastern India still continues its share of importance; it is a custom that during Dussehra you have to gift garments to family."
An industry expert on the briefing panel expanded on the structural growth of regional retail chains across the territory: "The biggest small-and-medium value chains are rising across Eastern India. Stores like V-Mart and Vishal Mega Mart are happening there. Somewhere down the line, it was an ignorance which led people to believe that the West had the only fashionable outlook. The loyalty and consistency have always been in the Eastern part of India. One domestic casual brand based out of Mumbai does almost 50% to 55% of its entire sales purely from Eastern India."
Menswear retains scale while tailoring reinforces exclusivity
Menswear remains the single largest apparel category in India at $38.5 billion (INR 3.24 lakh crore) in CY2025, accounting for 40.2% of consumer demand. Womenswear closely follows at $35.6 billion (INR 3.00 lakh crore, 37.2%), while kidswear accounts for $21.6 billion (INR 1.82 lakh crore, 22.6%). Uniquely, the survey also calculated India's institutional B2B uniform and workwear market at $2.1 billion (INR 17,600 crore), spanning industrial manufacturing ($574 million), hospitality ($347 million), corporate uniforms, healthcare, and gig-economy delivery fleets. This lifts total domestic sewn apparel production tracked by CMAI to $97.8 billion.
Within menswear, formal tailoring remains the largest individual sub-category at $17.11 billion, led by woven dress shirts ($8.05 billion) and trousers ($6.10 billion). However, casualwear is closing the gap at $15.47 billion, dominated by jeans ($7.90 billion) and knit T-shirts ($5.29 billion).
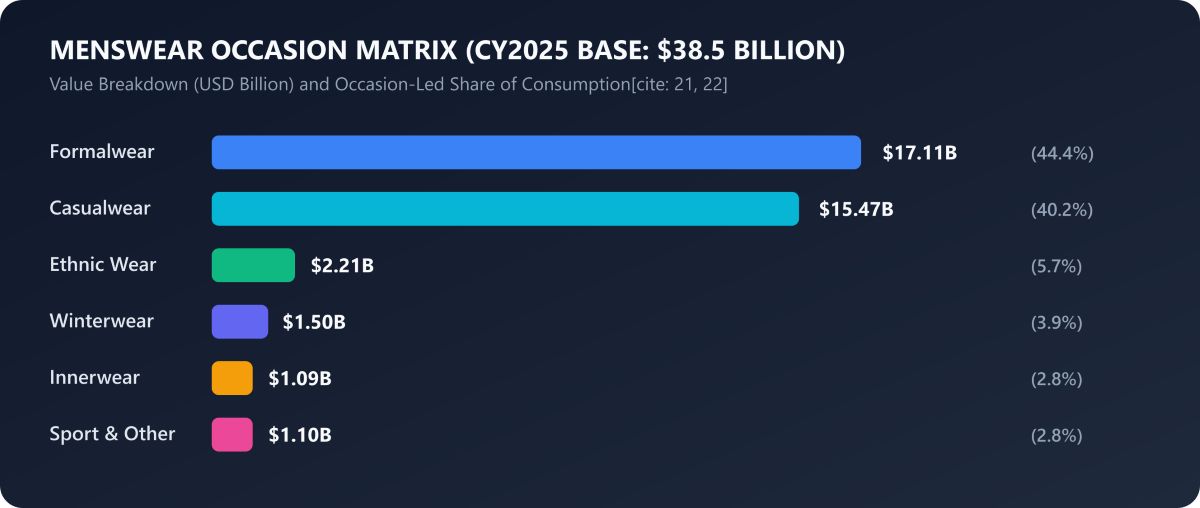
Behind the aggregate casualwear numbers lies a strategic shift in menswear: tailored clothing is regaining market share. Mehta highlighted this development during the presentation: "An interesting highlight is that demand for tailored clothing seems to be coming back. It is not that people are fed up with readymade garments. Rather, readymade garments have become far more democratised than what they used to be earlier. Therefore, those wanting to stand apart from the crowd and look exclusive are turning to tailored clothing. It is not the traditional local tailor returning, but more made-to-measure styling segments that are emerging."
Simultaneously, the Indian wedding calendar, processing between 9.5 million and 10 million celebrations annually; sustains robust demand for occasion ethnic wear like sherwanis, bandhgalas, and Nehru jackets ($2.21 billion). Describing the broader casualisation of the Indian wardrobe, Mehta noted: "One of the most significant shifts in India’s apparel consumption is the blurring of traditional category boundaries. Men’s wear is becoming more casual, comfortable, and versatile, with consumers seeking styles that can transition seamlessly between work, leisure, and social occasions."
The New Growth Engines: Kidswear and Womenswear
While menswear provides current baseline revenues, long-term velocity is concentrated in kidswear and womenswear. Kidswear is projected to record the fastest expansion of any demographic segment, advancing at a 9.4% CAGR between CY2025 and CY2029 to touch $33.9 billion. Womenswear is tracking an 8.9% CAGR toward $54.5 billion, while menswear will settle at an 8.5% CAGR to hit $57.9 billion.
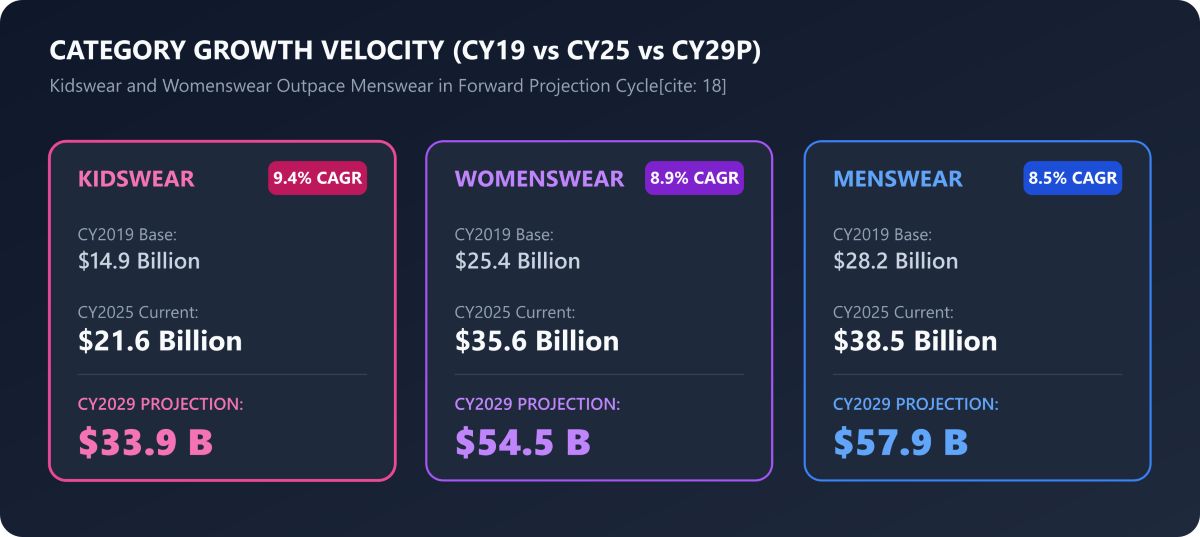
Kidswear's outperformance stems from fundamental demographic dynamics: children outgrow their garment sizes every six to nine months, creating non-discretionary replacement cycles. Beyond physical sizing, modern parents are allocating higher discretionary wallet share toward functional sportswear, character-merchandised apparel, and high-frequency casual clothing. Within kidswear, casualwear commands $9.39 billion, led by round-neck and collared T-shirts ($3.53 billion), jeans ($2.01 billion), and frocks ($1.69 billion), while school uniforms and structured shirts represent $6.98 billion.
In womenswear, ethnic wear remains the core foundation, capturing 59.5% ($21.17 billion) of total women's apparel. Sarees and Parihiya sarees form the single largest clothing category in the entire Indian garment economy at $10.43 billion (INR 87,890 crore), complemented by salwar suits ($5.22 billion).
However, female workforce entry and transit urban mobility have generated double-digit demand spikes for utility westernwear ($5.94 billion) and activewear. This lifestyle evolution has catalyzed Indo-Western styling, including formal kurtas paired with blazers, sarees worn over crop tops, and hybrid functional bottoms.
Hard to ignore
Ground Truth on Digital Hype: Physical stores control 83% of trade
The CMAI study delivers an empirical reality check to narratives predicting the rapid displacement of traditional retail by digital commerce. Offline brick-and-mortar storefronts settled 83% ($79.4 billion) of all apparel sold in India in CY2025. Digital channels captured only 17% ($16.3 billion).
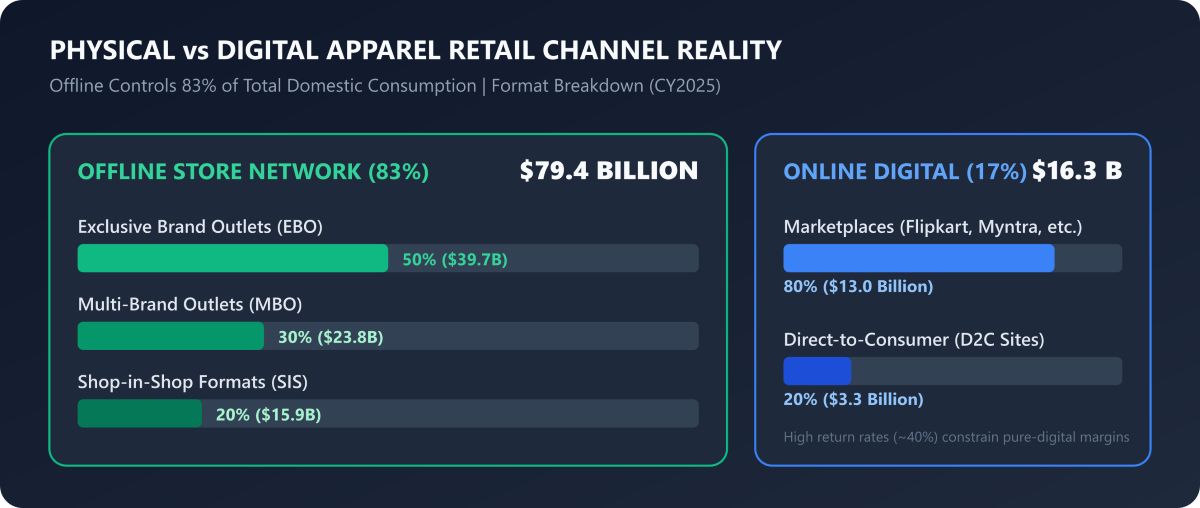
In the offline sector, exclusive brand outlets (EBOs) drive 50% ($39.7 billion) of trade as national apparel brands seek complete control over visual merchandising and brand messaging. Multi-brand outlets (MBOs) claim 30%, while shop-in-shop (SIS) retail corners account for 20%. Mehta explained the mechanics behind this store format split: "Shop-in-shops are growing particularly because most of them operate on a consignment basis, so the retailer does not carry the risk of unsold inventory. Meanwhile, EBOs are growing because brands feel their full product ranges do not get adequate presence in typical multi-brand stores, leading them to seek direct communication with consumers."
Online sales remain heavily consolidated, with major multi-brand marketplaces commanding 80% ($13.0 billion) of transactions, leaving independent direct-to-consumer (D2C) websites with the remaining 20% ($3.3 billion).
During the interactive session, Mehta pushed back against digital-first assumptions: "Thanks to the media, there is a lot of hype that online is killing the offline market and retailers are dying. But after all these years, online is not more than 17% of the total market. I have always been a strong believer in the resilience of the offline sector. Online will climb to a certain point, but beyond that, it will struggle to expand quickly. The proof is that almost all pure-play online brands; whether Snitch or Go Colors, have opened physical retail networks.”
Santosh Katariya addressed the underlying economics and return bottlenecks of digital retail: "Not a single online apparel platform is making money; practically 80% of the e-commerce apparel channel functions strictly as a liquidation mechanism for discounted end-of-season inventory. Less than 20% comes from fresh full-price merchandise.”
“Furthermore, in garments, consumers want to feel the texture and verify fit. Physical retail is about emotion, touch, and personal connection.", added Ankur Gadia, Vice President , CMAI.
Industry panellist Nikhil Furia, who is also incharge of PR for CMAI, added an operational perspective on digital convergence: "We have entered an age where every business must have a 360-degree presence where each medium complements the other. Small and medium store owners now run active Instagram accounts to engage local buyers who ultimately visit the shop in person. You cannot classify that purely as an online or offline sale; manufacturers must collaborate with retailers to deploy technology that drives overall store throughput."
CMAI: The Voice and anchor of India’s domestic garment industry
Established in 1963, the Clothing Manufacturers Association of India (CMAI) serves as the apex trade body representing over 7,000 apparel manufacturers and catering to more than 50,000 retailers across India. Spanning readymade garments, kidswear, and institutional apparel, CMAI leads national trade fairs like the National Garment Fair (NGF), drives the Eco-Stitch sustainability initiative, and guides policy and trade benchmarks across India’s core apparel manufacturing hubs.
 Get in Touch!

