Festive calendar disruption tests India's branded apparel market
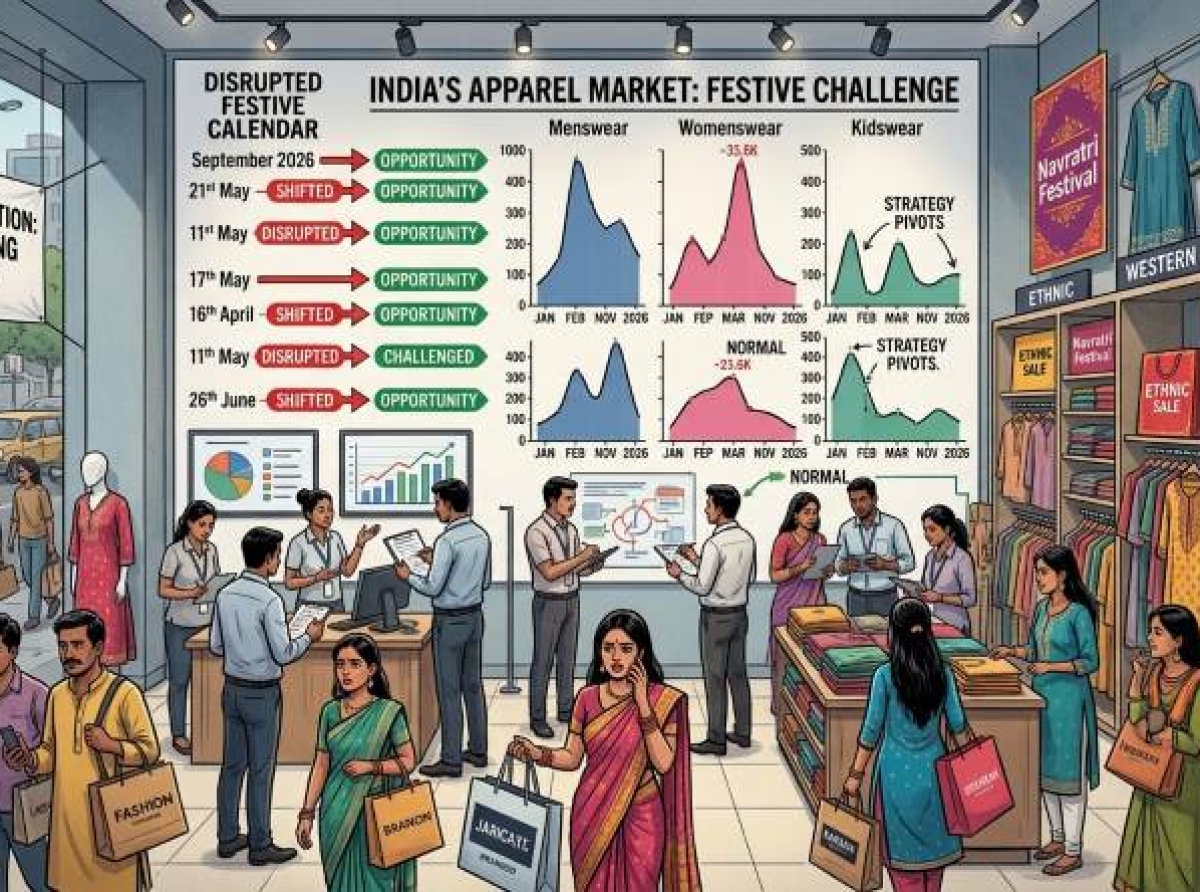
India’s branded apparel sector faced a seasonal demand disruption in Q2 FY27 as the postponement of festivals to October delayed wholesale stocking and retail inventory intake. However, the quarter exposed a clear divide in the industry: while value retailers continued growing their store networks, mid-to-premium brands focused on protecting margins, managing inventory and controlling working capital.
Kewal Kiran Clothing Ltd (KKCL), which owns Killer, Lawman, Integriti and Kraus, demonstrated this strategy, reporting a 5 per cent year-on-year increase in Q2 FY27 revenue to Rs 373 crore. EBITDA rose 12 per cent to Rs 80 crore, while EBITDA margin expanded 100 basis points to 21 per cent. Net profit increased 15 per cent to Rs 54 crore.
The performance suggests that disciplined pricing, operating efficiencies and product diversification can protect profitability even when seasonal demand shifts disrupt quarterly sales momentum.
Calendar shift delays demand
The July-September quarter traditionally benefits from advance stocking for Navratri and Durga Puja. This year, with both festivals falling in October, multi-brand outlets (MBOs), distributors and departmental stores deferred inventory purchases, affecting primary trade dispatches. Rather than using promotional discounts to stimulate sales, KKCL prioritised margins and overhead control. Gross margin improved 90 basis points to 43 per cent while profit after tax (PAT) margin grew 120 basis points to 14.5 per cent.
The first-half performance was stronger. H1 FY27 revenue increased 11 per cent to Rs 652 crore, EBITDA rose 19 per cent to Rs 133 crore and net profit advanced 19 per cent to Rs 94 crore. Gross margins improved 80 basis points to 43 per cent, indicating that profitability gains were not restricted to the September quarter.
Table: KKCL’s financial performance
|
Metric (Rs cr) |
Q2 FY26 |
Q2 FY27 |
YoY Change |
H1 FY26 |
H1 FY27 |
YoY Change |
|
Revenue from Operations |
Rs 354 |
Rs 373 |
+5% |
Rs 588 |
Rs 652 |
+11% |
|
Gross Profit |
Rs 149 |
Rs 160 |
+7% |
Rs 248 |
Rs 280 |
+13% |
|
Gross Margin (%) |
42.10% |
43.00% |
+90 bps |
42.20% |
43.00% |
+80 bps |
|
EBITDA |
Rs 71 |
Rs 80 |
+12% |
Rs 113 |
Rs 133 |
+19% |
|
EBITDA Margin (%) |
20.00% |
21.00% |
+100 bps |
19.20% |
20.40% |
+120 bps |
|
Profit After Tax (PAT) |
Rs 47 |
Rs 54 |
+15% |
Rs 79 |
Rs 94 |
+19% |
|
PAT Margin (%) |
13.30% |
14.50% |
+120 bps |
13.40% |
14.40% |
+100 bps |
The numbers point to business prioritising earnings quality over short-term revenue acceleration. Its performance also reflects the importance of maintaining distribution relationships and inventory discipline during periods of uneven consumer demand.
Retail strategies change
The contrast across apparel companies highlights different approaches to growth. Trent continued to benefit from Zudio's aggressive value-fashion expansion and Westside's established retail presence, delivering reported consolidated revenue growth of more than 20 per cent.
At the other end, Raymond Lifestyle faced operating margin pressure as fabric and raw material costs, manufacturing expenses and store expansion overheads weighed on profitability. Its experience underlines the challenges facing formalwear and mid-premium apparel businesses when input costs rise faster than achievable price increases. KKCL's performance sits between these models, with a focus on profitable growth rather than expansion at any cost.
Table: Q2 FY27 apparel industry comparison
|
Company |
Q2 revenue |
Operating margin |
Strategic driver |
|
Kewal Kiran Clothing (KKCL) |
+5% YoY ( Rs 373 cr) |
Expanded to 21% (+100 bps) |
Margin protection, selective credit, product mix |
|
Trent Ltd (Westside / Zudio) |
+20% to +24% YoY |
Range-bound / format mix |
Value fashion rollouts, high inventory churn |
|
Raymond Lifestyle |
Mid-single-digit growth |
Compressed (80-120 bps) |
Fabric inflation, store overheads, formalwear lag |
|
Apparel Retail Sector Average |
+4% to +8% YoY |
Stable to slightly lower |
Pre-festive stocking deferral to October |
Industry data also indicate that apparel store footfalls declined 3-6 per cent in July and August, due to erratic monsoons and fewer weddings. Retailers responded by limiting advance inventory commitments and controlling distributor credit exposure. This suggests that the slowdown was partly calendar-driven rather than evidence of a fundamental deterioration in demand. However, the ability to convert the subsequent festive recovery into profitable sales remains the more important test.
Kraus broadens the portfolio
KKCL's diversification into women's casualwear through Kraus Jeans has added another dimension to its growth strategy. Associated with men's denim through Killer for all these years, the company has been increasing its presence across women's casualwear, fast-fashion denim and modern retail formats. Kraus has helped balance slower wholesale demand in the men's segment, while giving access to large-format stores and a wider consumer base.
The acquisition also reduces dependence on a single product category and creates opportunities to improve distribution productivity without relying exclusively on discount-led volume growth.
"Q2 was a resilient quarter delivered against a challenging external environment, as key festive occasions such as Navratri and Durga Puja shifted into October," opines Hemant Jain, Joint Managing Director of KKCL.
He added that the company remained focused on growth, profitability and operational discipline, while highlighting Kraus's sales growth and EBITDA margins. The significance is clear: portfolio diversification can cushion seasonal volatility, provided new categories contribute to margins rather than merely adding turnover.
Festive recovery to test growth
The October convergence of Navratri, Durga Puja and Diwali is expected to support a recovery in primary trade billings and retail offtake during Q3 FY27. An extended winter wedding season across northern, central and western India could sustain demand into January. Industry projections place annual revenue growth for mid-tier and premium casualwear at 12-15 per cent in FY27. However, higher retail rentals, particularly in urban malls and high-street locations, remain a structural cost challenge.
For brands such as KKCL, established distribution networks across Tier II, III markets, controlled working capital and a zero net-debt balance sheet provide an advantage. Its planned addition of 50-70 net stores annually will nevertheless require careful capital allocation to preserve operating returns.
The broader lesson from Q2 is that apparel companies cannot rely on festive-led volume growth alone. With inventory discipline, input costs and store economics increasingly influencing profitability, the ability to protect margins through demand fluctuations is becoming a more meaningful measure of business strength.
 Get in Touch!

